A clear path to your front door.
Personalised mortgage advice for New Zealanders. We navigate the banks so you can focus on finding the right place to call home.
How we help you get ahead
Whether you are stepping into your first home, next home or expanding your property portfolio, our process is designed to be calm and capable.
First Home Buyers
Navigating KiwiSaver withdrawals, the Kainga Ora First Home Loan, and low deposit options to get you on the ladder sooner.
- + First Home Buyer Specialist Advice
- + Pre-approval Strategy
Refixing & Top-ups
Do not just roll over with your current bank. We negotiate the best rates and cash incentives every time you refix.
- + Cash back incentives
- + Debt Consolidation
Property Investment
Structuring your loans to maximise tax efficiency and cash flow for long term wealth creation across NZ.
- + Equity Release
- + Lending structure audits
Stepping into your first home
First time around the table is where the questions pile up. We settle the deposit, the paperwork, and the schemes you actually qualify for before you fall for a place.
Get deposit readyDeposit and KiwiSaver
We confirm exactly what you can withdraw and when, so your deposit number is solid before you go shopping for a home.
Kainga Ora First Home Loan
The scheme behind most 5 percent deposits in New Zealand. We work through the income caps, ownership history and residency rules with you, then confirm which lenders are taking applications before you fall for a place.
Pre-approval before you bid
A clear borrowing figure you can carry into an auction or negotiation, with the conditions already untangled.
Low deposit lending
We know which lenders are still active below 20 percent and what each one wants to see in your application.
Moving to your next home
Up-sizing, down-sizing, or relocating. Selling and buying at the same time is where most people need a plan, so we map the timing first and the lending second.
Plan your moveSell first or buy first
We work out which order suits your finances and the local market, then build the loan around that sequence.
Bridging and settlement gaps
Short term structures that keep you covered while the two settlements line up, without a rush of paperwork at the end.
Portability
In many cases your existing rate and terms can move across with you, so you keep the deal you already negotiated.
Equity and the new deposit
We confirm how much of your current equity is genuinely available to you before you go shopping at auction.
Growing your portfolio
Every extra property changes the maths. We look at how lenders treat investor debt, what your cash flow can genuinely carry, and where your equity is sitting before you commit to another property.
Talk through your numbersInvestor borrowing capacity
Lenders assess rental income differently to your own pay. We work out the figure you genuinely qualify for before you buy another property.
Equity as your next deposit
Using the equity you already have as the deposit for the next purchase, and how to structure it so nothing ties your hands later.
Rates, terms, and lender appetite
Investor lending criteria move often. We keep track of which banks are still keen and what each one will and will not count.
Optimise your lending structure
Interest only or principal and interest, fixed for how long, where to spread your lending risk and across which lenders are all key to a successful property portfolio.
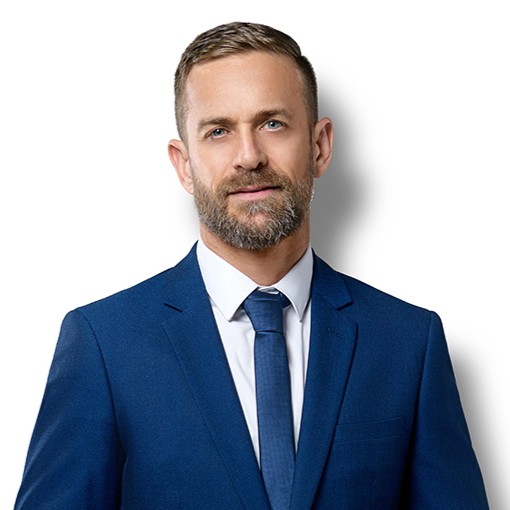
Kyle Reardon, Mortgage Adviser
"Kyle was absolutely brilliant throughout the entire mortgage process. He took the time to really listen to our goals and provided expert advice on how to restructure our mortgage in a way that truly benefits us. Everything was tailored specifically to our needs, and he even went above and beyond by offering additional insights to help us make the most of our financial situation. Highly recommend Kyle to anyone looking for a knowledgeable, trustworthy, and proactive mortgage broker."
Common Questions
Does your service cost me anything?+
How much deposit do I need?+
What does pre-approval actually give me?+
Can I refinance or change lenders?+
I am a first home buyer, what help is out there?+
Ready to start your journey?
Book a no obligation consultation today and get a clear picture of your options.
Book a chat with KylePick a time that suits you